
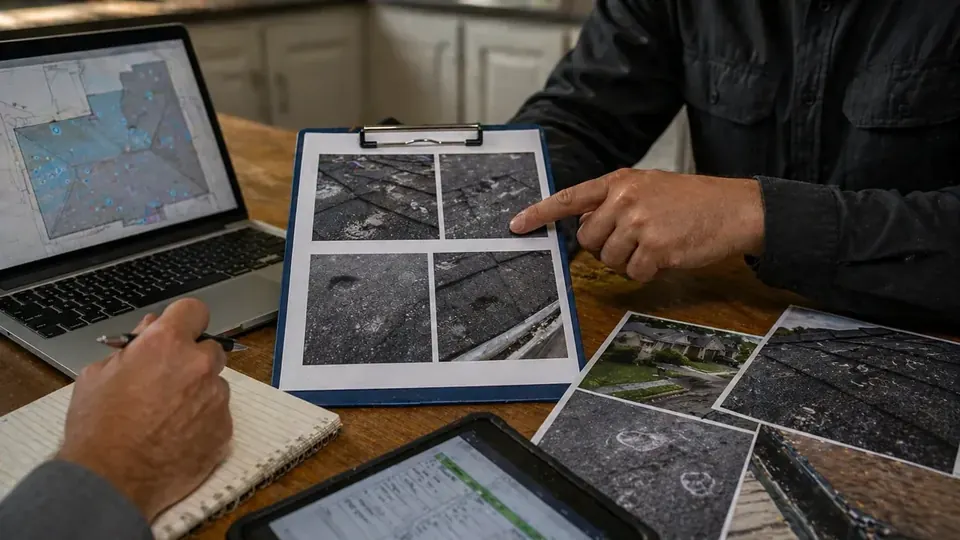
Insurance claims are supposed to bring relief after property damage. In practice, they often bring delays, confusing letters, and estimates that do not match what the repairs actually cost. McAllen Public Adjuster exists to give homeowners and business owners in McAllen, Hidalgo County, and the surrounding Rio Grande Valley (RGV) someone in their corner during that process: a licensed public adjuster who works for the policyholder, not the insurance company.
Your insurer has its own adjusters, estimators, and claim reviewers. We believe you deserve informed representation, too.
Who operates McAllen Public Adjuster
McAllen Public Adjuster is a public adjusting service of Rise Public Adjusting LLC, licensed by the Texas Department of Insurance (TDI license #3356839). We serve McAllen, Hidalgo County, and nearby Rio Grande Valley communities, and we meet clients at their damaged property rather than at a storefront office.
Claims are led by Joseph Dittman, a licensed Texas public adjuster, certified insurance appraiser, insurance umpire, and expert witness. His background includes carrier-side adjusting, public adjusting, appraisal work, expert witness support, and hands-on construction experience, across residential, commercial, storm, hail, wind, water, fire, hurricane, and catastrophe losses. He also reviews the articles published on this site.
Who we serve
No two McAllen claims are the same. A hailstorm in April, a burst pipe during a hard freeze, a kitchen fire, or a wind event that peels shingles off a two-story home all raise different questions. We work with:
- Homeowners dealing with storm, fire, water, or structural damage
- Business owners facing property losses and interrupted operations
- Property managers handling multi-unit or commercial claims
- Landlords working through coverage questions on rental properties
See our full list of claim services for details on residential claims, commercial claims, and specific loss types.
How a public adjuster is different
Most people meet an insurance adjuster only after a loss, and that adjuster works for the insurance company. A public adjuster is licensed to represent the policyholder in the same claim.
| Topic | Insurance company adjuster | Public adjuster |
|---|---|---|
| Who they represent | The insurer | The insured policyholder |
| Who pays them | The insurance company (staff or independent firm) | The policyholder, under a written contract |
| Main task | Evaluate the claim under the insurer's guidelines | Document and present the full covered loss for the policyholder |
| Workload focus | Often many claims at once after a storm | Your claim, your policy, your property |
| Licensing in Texas | Adjuster license | Public adjuster license under Insurance Code Chapter 4102 |
For a closer look at the difference on storm losses, read public adjuster vs. insurance adjuster for hail claims.
How Texas regulates public adjusters
Public adjusting is a regulated profession in Texas. Public adjusters are licensed and overseen by the Texas Department of Insurance under Texas Insurance Code Chapter 4102. A few rules matter most to policyholders:
- Written contract. Representation starts only with a written contract using TDI-approved terms. Fees are disclosed in a written contract before any work begins; Texas law caps public adjuster compensation at 10% of the insurance settlement.
- 72-hour rescission. You may cancel the contract within 72 hours of signing it.
- "We represent the insured only." Texas public adjuster contracts must state this plainly. We do not work for insurers.
- No repair conflicts. A public adjuster may not take part in repairing or rebuilding a property on a claim they adjust.
You can verify any public adjuster's license through TDI's online license lookup before you sign anything. We encourage it.
Our approach
We do not use shortcuts or one-size-fits-all claim packages. Every property, policy, and loss is handled on its own facts. Our process typically includes:
- Inspection. A thorough look at visible and hidden damage, including roofs, interiors, and systems.
- Documentation. Photos, measurements, and notes, often supported by Xactimate estimating software and Matterport 3D imaging.
- Policy review. Reading your declarations, coverages, endorsements, deductibles, and exclusions.
- Claim presentation. A detailed estimate and supporting file submitted to the insurer.
- Negotiation and follow-up. Communicating with the insurer, answering requests, and pursuing supplements or appraisal when appropriate.
We stay involved from start to finish. You will know who is handling your claim and what happens next.
Transparency you can count on
One of the biggest frustrations policyholders describe is not knowing where their claim stands. We make communication a priority:
- Honest assessments of a claim's strengths and limitations
- Regular updates as the claim moves forward
- Clear explanations of timelines and next steps
- Straight answers, even when they are not what you hoped to hear
Sometimes the honest answer is that a public adjuster is not needed. If your insurer's offer looks fair or the loss is small compared with your deductible, we will tell you.
Ethics: what we never do and what we do
We never:
- Inflate damages or add items that are not part of the loss
- Misrepresent facts to an insurer
- Promise a specific settlement amount or outcome
- Pressure anyone into signing a contract
We do:
- Present legitimate claims thoroughly and accurately
- Respond to unfair or unsupported denials with documentation
- Hold the claim to the terms of the policy you paid for
What we do not do
Knowing our limits protects you. We are not attorneys. We do not give legal advice, file lawsuits, or handle bad-faith litigation; if your situation needs a lawyer, we will say so and suggest you consult a Texas attorney. We are not contractors. We do not perform repairs, and we do not take a role in rebuilding a property on a claim we adjust. You keep full control over who repairs your home or building.
When to call a public adjuster
Some people call too late, after a settlement has been accepted on incomplete information. Others call early and avoid common mistakes. Consider reaching out if:
- Your claim was denied or underpaid
- The insurer keeps delaying the claim or changing adjusters
- You are being asked for extensive documentation and are unsure what to send
- The loss is large, complex, or involves hidden damage
- You want an independent review of the insurer's estimate before accepting it
Help is available at most stages of a claim, though policy deadlines still apply.
Our commitment to McAllen
McAllen property owners face real weather risks: spring hail that peaks in April and May, severe straight-line winds, tropical systems such as Hurricane Dolly in 2008 and Hurricane Hanna in 2020, flash flooding, and the February 2021 freeze. Many local homes are slab-on-grade with composition shingle roofs and stucco or brick veneer; many businesses have metal or low-slope roofs. Understanding how those buildings get damaged, and how insurers tend to evaluate that damage, is part of the work.
Our commitment is simple: communicate clearly, act ethically, document carefully, and give you an honest view of your claim. If you are unsure whether your claim is being handled fairly, start with a Free Claim Review or call +1 (832) 503-5866.
Frequently Asked Questions
Who owns and operates McAllen Public Adjuster?
McAllen Public Adjuster is a public adjusting service of Rise Public Adjusting LLC, which is licensed by the Texas Department of Insurance (license #3356839). Claims are handled by licensed Texas public adjusters, including Joseph Dittman.
How much does a public adjuster cost in Texas?
Fees are disclosed in a written contract before any work begins; Texas law caps public adjuster compensation at 10% of the insurance settlement. If your insurer pays or commits in writing to pay policy limits within 72 hours after the loss is reported, a percentage fee is not allowed. Our Free Claim Review costs nothing and carries no obligation.
Is a public adjuster the same as an attorney?
No. A public adjuster prepares, documents, and negotiates the property insurance claim for the policyholder. We do not give legal advice, file lawsuits, or represent anyone in court. For questions about suits, bad faith, or legal deadlines, talk to a Texas attorney.
Can I cancel a public adjuster contract after signing?
Yes. Texas public adjuster contracts must allow the insured to rescind the contract within 72 hours of signing. The contract itself explains how to do this.
Do you do the repairs on my property?
No. Texas law does not allow a public adjuster to take part in the repair or reconstruction of a property on a claim they adjust. You choose your own contractor; we focus on the claim.